

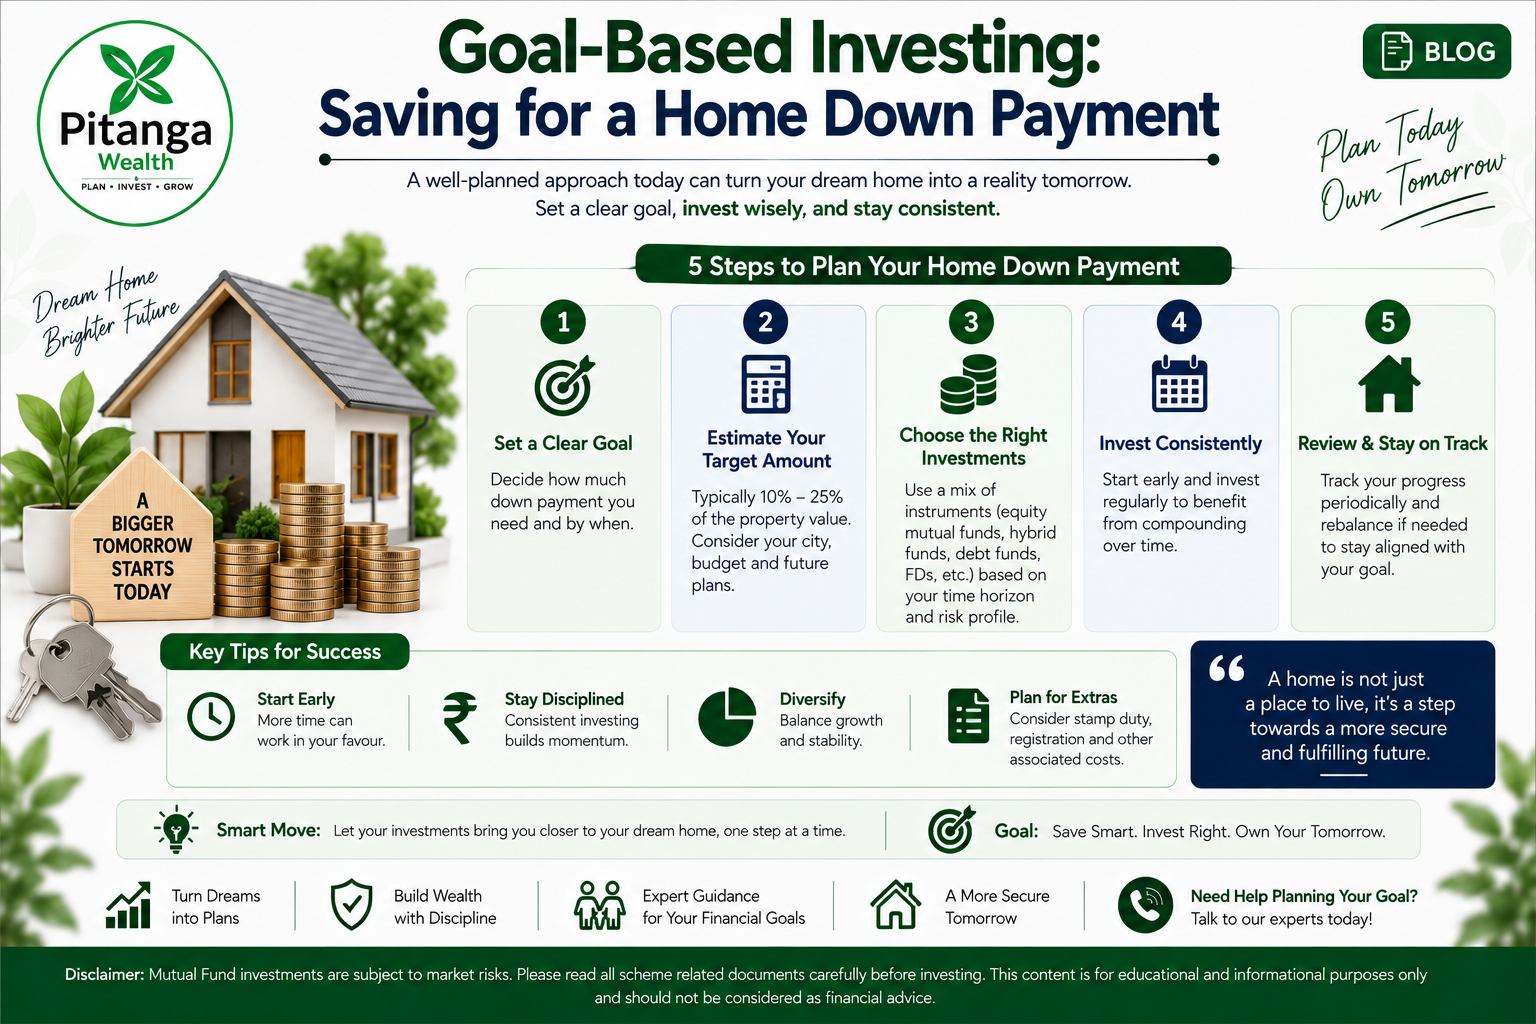
A young couple I know started saving for a home down payment the way they’d been told to save for everything else: put it in equity mutual funds and let it grow. Two and a half years in, close to the time they’d planned to actually make an offer on a flat, the market went through a rough patch. Their down payment corpus was suddenly worth noticeably less than it had been six months earlier, at exactly the moment they needed the full amount. They ended up delaying the purchase by nearly a year, waiting for the portfolio to recover.
Saving for a home down payment isn’t the same problem as saving for retirement, and treating it with the same playbook is where a lot of people run into trouble. It’s a goal with a specific, often semi-fixed deadline and a large lump sum required all at once — which changes almost everything about how the money should be invested along the way.
What Makes This Goal Different
A home down payment usually sits in an awkward middle zone: not short enough to just sit in a savings account, but not long enough to comfortably ride out full market volatility the way a 15-year goal can. Most people saving for a home down payment are working with a 2-to-5-year horizon, which is exactly the range where the wrong asset choice can do real damage — too conservative, and inflation and rising property prices erode your progress; too aggressive, and a market dip right before you need the money can force a delay or a loss, as happened to the couple above.
Step 1: Get Honest About the Real Target Amount
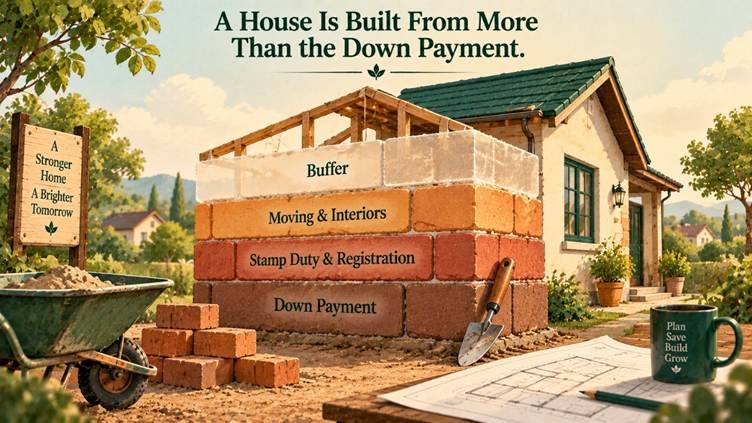
Most people underestimate what they’re actually saving for. The commonly cited “20% down payment” figure is just the starting point — on top of that, there’s stamp duty and registration charges (which can add a meaningful percentage on top of the property value depending on your state), brokerage if applicable, and often immediate post-purchase costs like basic interiors or moving expenses that people don’t factor in until they’re already at the finish line.
Before deciding how to invest, it’s worth working out a realistic total — not just the headline down payment percentage — so the goal you’re actually investing toward reflects what you’ll really need to have in hand.
Step 2: Match Your Investment Choice to How Much Time You Actually Have
This is the step that tripped up the couple in the opening story, and it’s the single most important decision in saving for a home down payment.
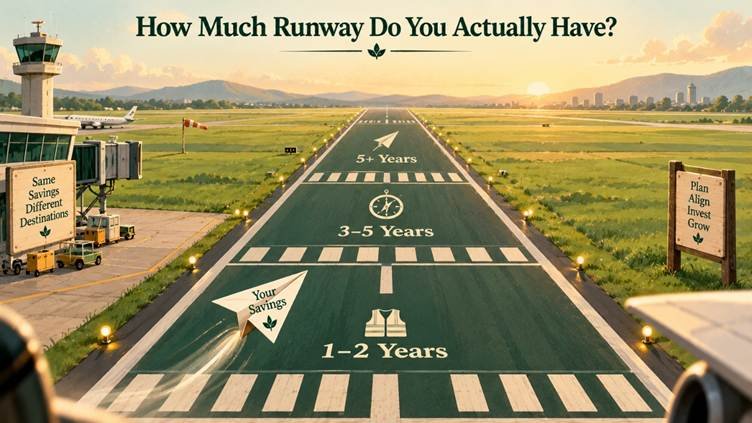
If you’re 1–2 years out: This is a short enough horizon that capital protection generally matters more than growth potential. Liquid funds, short-duration debt funds, or similar lower-volatility instruments are commonly used here, since there’s limited time to recover from a market downturn if one happens right before you need the funds.
If you’re 3–5 years out: There’s slightly more room to consider a measured allocation toward equity or hybrid funds, since a longer runway allows more time to potentially ride out volatility — though even here, many financial plans still lean conservative as the purchase date gets closer, rather than staying fully equity-exposed until the very end.
If you’re 5+ years out: A higher equity allocation becomes more reasonable to consider, similar to how other long-term goals are approached, with a shift toward debt instruments beginning a few years before the actual purchase.
None of this guarantees an outcome — markets can behave unpredictably over any period — but time horizon is the single biggest factor in how much risk is reasonable to take with money you have a specific, dated need for.
Step 3: Avoid the Two Opposite Traps
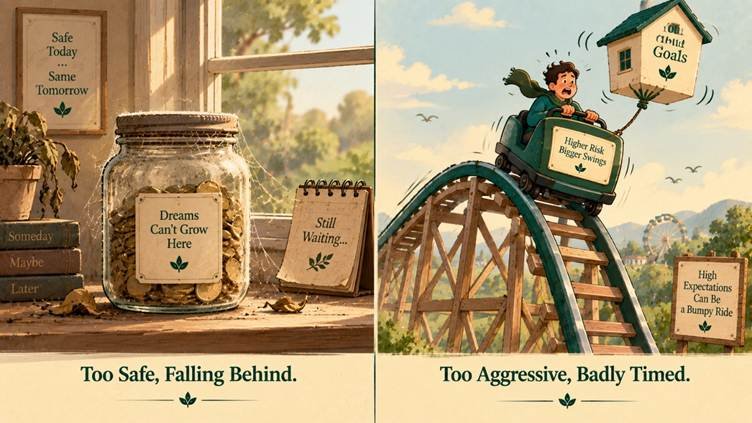
Trap one: keeping everything in a savings account or low-yield fixed deposit for years. This feels safe, but property prices and overall costs tend to rise over time, and money that isn’t growing at a comparable pace effectively loses ground against the target, even without any market risk involved.
Trap two: chasing higher returns through aggressive equity exposure too close to the purchase date. This is what happened in the story above — a goal with a near-certain deadline was invested as though it had an open-ended, flexible timeline, and the mismatch created real financial stress when the timeline didn’t bend but the market did.
The right approach for saving for a home down payment usually sits between these two extremes, calibrated specifically to how much time is actually left.
Step 4: Build In a Buffer, Not Just the Bare Minimum
One detail that separates careful saving for a home down payment from a rough guess is padding the target itself. Because a home purchase has so many moving costs beyond the headline down payment figure, it’s worth targeting somewhat more than your initial estimate rather than the bare minimum. Because a home purchase has so many moving costs beyond the headline down payment figure, it’s worth targeting somewhat more than your initial estimate rather than the bare minimum. Interest rates, property prices, and your own preferences (a slightly bigger flat, a better location) can all shift the number upward between when you start saving and when you’re actually ready to buy. A buffer of even 10–15% above your initial estimate can be the difference between a smooth purchase and a stressful scramble for extra funds at the last minute.
Step 5: Automate It, and Shift the Mix as the Date Gets Closer
Automating this process is what actually makes saving for a home down payment sustainable month after month, rather than something you have to consciously remember every time. A dedicated SIP for this specific goal — separate from other investments — keeps progress visible and makes it easier to track against your target. A dedicated SIP for this specific goal — separate from other investments — keeps progress visible and makes it easier to track against your target. As the purchase date approaches, gradually shifting the allocation toward more conservative instruments (similar to the glide-path approach used for other time-bound goals) reduces the chance that a late market swing derails a purchase you’re otherwise ready to make.
Common Mistakes People Make
Starting too late relative to the purchase timeline. A shorter runway limits your options and often forces a more conservative approach than you might have preferred with more lead time.
Ignoring stamp duty, registration, and post-purchase costs. These add up to a meaningful amount that’s easy to forget when focused only on the down payment percentage itself.
Treating this like a long-term goal when the timeline is actually short. This is the core mistake from the opening story, and it’s one of the more financially painful ones to make, precisely because the deadline for a home purchase often can’t simply be pushed back the way other goals can.
Panic-selling or panic-holding when the market moves. Both stopping a SIP during a dip and refusing to shift toward safer assets as the deadline nears can work against the plan, just in opposite directions.
Frequently Asked Questions
How far in advance should I start saving for a home down payment? Earlier generally gives you more flexibility in how you invest, since a longer runway allows a temporarily more growth-oriented approach before shifting conservative closer to the purchase. Starting even a few years ahead, rather than scrambling in the final year, tends to produce a smoother outcome.
Should I use a SIP or a lump sum for this goal? Both can work depending on how the funds become available to you — a regular SIP suits ongoing monthly savings, while a lump sum (a bonus, for instance) might be deployed differently depending on how much time is left until the purchase.
Is it better to keep down payment savings completely separate from other investments? Many people find it easier to track progress and avoid dipping into the fund for other purposes when it’s kept in a dedicated, clearly labeled investment rather than blended into general savings.
What if I don’t know exactly when I’ll buy? If your timeline is genuinely uncertain, it’s often safer to lean toward more conservative instruments than you might otherwise choose, precisely because you can’t rely on a longer horizon to smooth out short-term volatility if your plans move up unexpectedly.
Should I include stamp duty and registration in my down payment target, or budget for those separately? Either approach can work, but including them in your overall target — rather than treating them as an afterthought — tends to produce a more accurate goal and reduces the chance of a last-minute funding gap.
Is real estate price inflation something I should actually factor into my savings target? Yes — property prices in many Indian cities have historically tended to rise over time, so it’s worth periodically revisiting and adjusting your target amount rather than saving toward a number fixed at the very start of your journey.
If you’re saving for a home down payment and want help balancing growth potential against how much time you actually have, our team at Pitanga Wealth can help you build a plan around your specific timeline.
Mutual Fund investments are subject to market risks. Read all scheme-related documents carefully before investing. The information in this article is for educational purposes only and should not be construed as investment advice or a recommendation to invest in any particular scheme or product. Pitanga Wealth is an AMFI-Registered Mutual Fund Distributor (ARN-134606).
Written by the Pitanga Wealth team.
📲 Planning a big purchase like this one? We share practical, goal-based money planning tips on Instagram — follow @pitangawealth to stay on track.
This article is for educational and informational purposes only. It is not investment, tax, legal or insurance advice. Consider your circumstances and relevant documents before making a financial decision.