

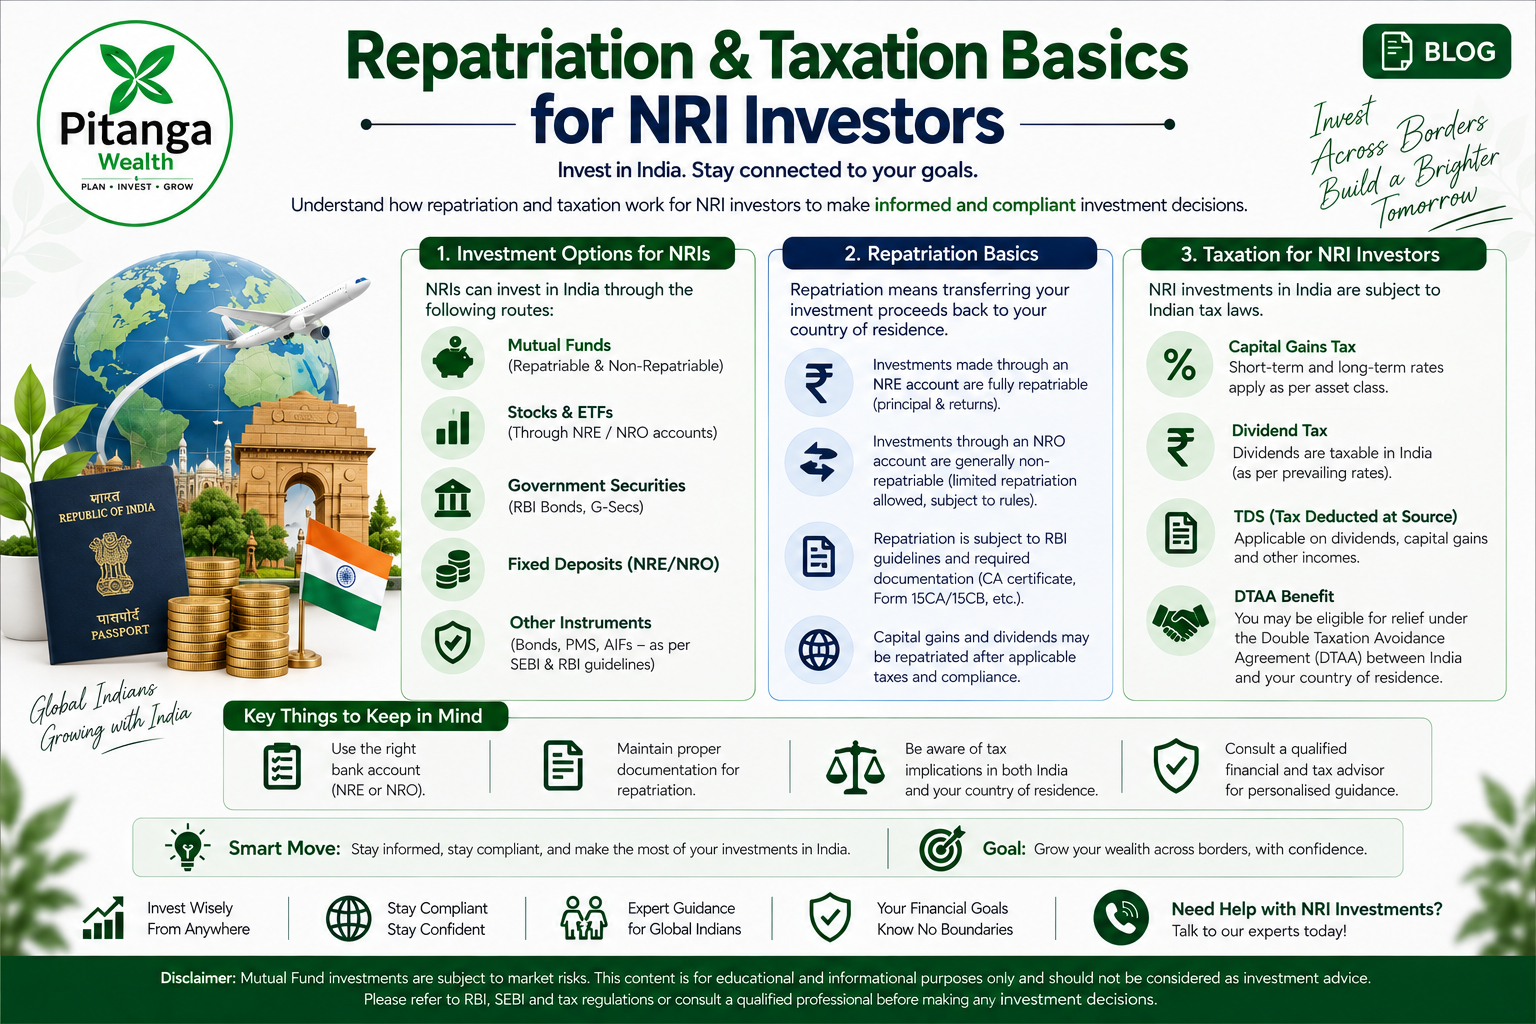
Repatriation and taxation for NRI investors is one of those topics that stays theoretical right up until the moment you actually need to move money out of India — and then it becomes urgent very quickly. An NRI friend based in Singapore once told me about the time she decided to sell some of her Indian mutual fund holdings and move the proceeds abroad to help fund a down payment. She assumed it would work like any other bank transfer — a few clicks, maybe a day’s wait. Instead, she spent close to three weeks going back and forth with her bank and a chartered accountant over a form she’d never heard of before, while her down payment deadline crept closer.
This guide walks through what actually happens, so it isn’t a surprise when you need it.
What Repatriation Actually Means
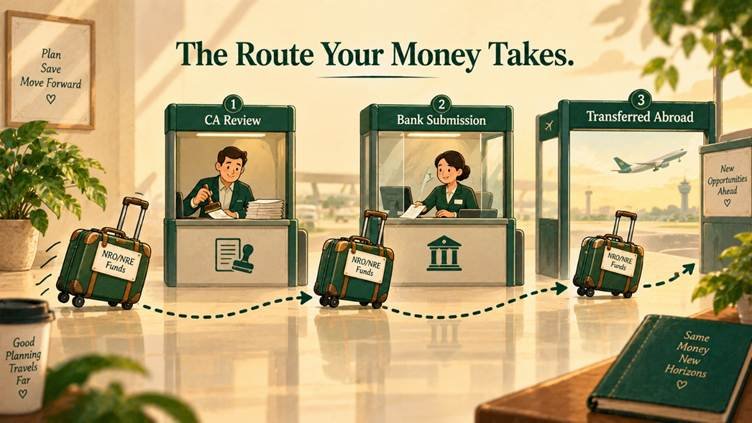
Repatriation simply means transferring money from India to a bank account abroad through legitimate banking channels, in compliance with FEMA (Foreign Exchange Management Act) regulations. It’s not inherently complicated — banks handle these transfers regularly — but the specific rules and documentation depend on where the money came from and how much you’re moving.
Repatriable vs Non-Repatriable: It Starts With Your Account Type
This is where repatriation and taxation for NRI investors connects directly back to the account you originally invested through. If you’re not clear on the difference between an NRE and NRO account, it’s worth understanding that first, because it determines almost everything about how repatriation works for you:
- Funds in an NRE account are generally fully and freely repatriable — both the principal and any interest or investment gains, since the money originated abroad in the first place.
- Funds in an NRO account are subject to repatriation limits and additional documentation, since NRO accounts are meant to hold India-sourced income, and the rules are structured accordingly.
The USD 1 Million Limit for NRO Repatriation
Under current RBI rules, NRIs can generally repatriate up to USD 1 million per financial year from their NRO account balances, subject to submitting the required tax documentation and meeting applicable conditions. This limit applies specifically to NRO funds — NRE repatriation isn’t subject to this cap in the same way, since it’s considered your own foreign-sourced money moving back out.
It’s worth noting that RBI limits and rules are subject to change over time, so confirming the current applicable limit with your bank before planning a large transfer is a sensible step rather than relying on a figure from an old article or conversation.
The Paperwork: Form 15CA and Form 15CB
This is the part that caught my friend off guard, and it’s genuinely the crux of repatriation and taxation for NRI investors in practice:
- Form 15CA is a declaration you (or your bank, depending on the process) file online, confirming the nature of the remittance and its tax treatment.
- Form 15CB is a certificate from a chartered accountant, confirming that applicable taxes have been paid or accounted for on the amount being remitted. This is typically required above certain remittance thresholds, and the specific requirement can vary based on the nature and size of the transaction.
Getting Form 15CB organised takes time, since it requires a CA to review your specific transaction, applicable tax provisions, and documentation before certifying it. Starting this process only after you urgently need the funds abroad — as happened with my friend — is exactly what turns a routine transfer into a multi-week wait.
How Capital Gains Are Actually Taxed for NRIs
Taxation is really the second half of repatriation and taxation for NRI investors, and it’s worth understanding before, not after, you sell anything. When an NRI sells an investment — mutual fund units, for instance — the resulting capital gain is generally taxed under the same broad capital gains framework that applies to resident investors, with short-term and long-term treatment depending on the holding period and asset type, as per current tax provisions. The key practical difference for NRIs is TDS (tax deducted at source), which is typically deducted on the transaction itself, often at rates that differ from what a resident investor would see on the identical transaction.
This means an NRI often experiences tax being withheld upfront on redemption, rather than paying it later while filing a return, which is a structurally different experience from how many resident investors encounter capital gains tax. Because these rates and provisions can change and depend on your specific circumstances, this is an area where confirming current rules with a CA familiar with NRI taxation is worth doing before a transaction, not after.
DTAA: Avoiding Being Taxed Twice on the Same Income
India has Double Taxation Avoidance Agreements (DTAAs) with many countries, which can reduce or offset tax paid in India against your tax liability in your country of residence, depending on that country’s specific treaty terms. To claim this benefit, NRIs typically need to provide:
- A Tax Residency Certificate (TRC) from the tax authority of their country of residence
- Form 10F, a self-declaration providing additional details not captured in the TRC
Without these documents in place at the time of the transaction, the default (and often higher) TDS rate may apply, even if you’d otherwise be eligible for DTAA relief — meaning the paperwork isn’t just a formality, it can directly affect how much tax is withheld upfront.
A Quick Note on Property vs Financial Investments
Repatriation and taxation for NRI investors selling immovable property is a distinct topic from financial investment repatriation, involving its own specific set of rules and documentation, including different repatriation limits and conditions under FEMA — worth treating separately rather than assuming the same process applies to both.
A Simple Way to Stay Prepared in Advance
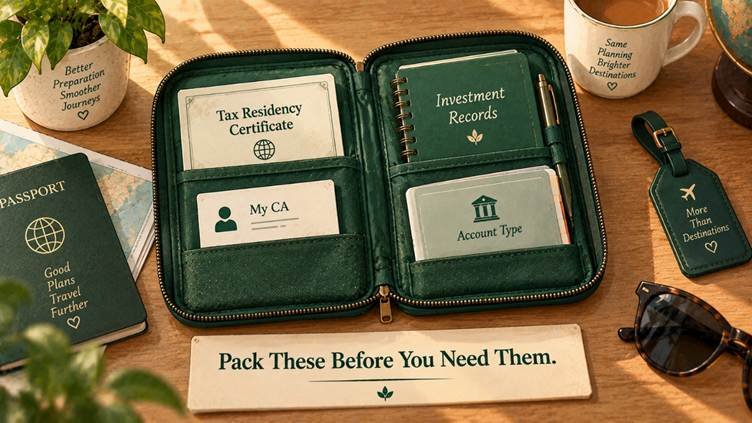
Rather than starting from scratch when you actually need to repatriate funds, it helps to have a few things organised ahead of time:
- A current Tax Residency Certificate from your country of residence, renewed as needed rather than requested only when a transaction is imminent
- A CA who’s familiar with NRI taxation and repatriation, ideally engaged before you need to move money, not after
- Records of your original investment amounts and acquisition dates, which matter for calculating capital gains accurately
- A basic understanding of which of your accounts (NRE or NRO) hold which funds, since this determines your repatriation route from the outset
Having these in place doesn’t eliminate the paperwork, but it typically turns what could be a multi-week process into something considerably faster.
At its core, repatriation and taxation for NRI investors comes down to two things: having the right documents ready, and understanding which account your money is sitting in before you need to move it.
Common Mistakes That Cause Delays
Not starting the Form 15CB process early enough. This is the single most common cause of delay, since it requires CA involvement and documentation review that simply takes time.
Assuming NRE and NRO funds follow identical repatriation rules. They don’t, and confusing the two can lead to unnecessary paperwork or, worse, an incorrectly filed declaration.
Not maintaining a Tax Residency Certificate in advance. Waiting until the moment of transfer to request a TRC from your country of residence’s tax authority can add significant delay, since obtaining one isn’t always instant.
Losing track of original investment documentation. Cost basis and acquisition records matter for calculating capital gains accurately — not having these organised can complicate both the CA certification and your own tax filing.
Assuming repatriation rules are the same as when they last checked. FEMA and tax rules are revised periodically, and relying on outdated information is a common, avoidable source of confusion.
Frequently Asked Questions
How long does the repatriation process typically take once all documents are ready? This varies by bank and the complexity of the transaction, but having Form 15CB, your TRC, and supporting documents ready in advance meaningfully shortens the process compared to starting the paperwork only when you need the funds.
Do I need Form 15CB for every remittance, regardless of amount? Requirements vary based on the remittance amount and nature of the transaction under current rules — smaller remittances may have different documentation requirements than larger ones. It’s worth confirming the current threshold with your bank or CA rather than assuming a fixed rule.
Can I claim DTAA benefits without a Tax Residency Certificate? Generally, the TRC (along with Form 10F) is required to claim DTAA relief; without it, the default TDS rate is more likely to apply, even if you’d otherwise qualify for treaty benefits.
Is repatriation from an NRE account really unrestricted? NRE account funds are generally freely repatriable, reflecting that the money originated outside India, but it’s still worth confirming your bank’s specific process and any documentation they require for the transfer itself.
What happens if I don’t repatriate my NRO funds within a financial year — does the limit reset? The USD 1 million limit applies per financial year, so unused capacity in one year generally doesn’t carry forward, though it’s worth confirming current rules with your bank since provisions can be revised.
Should I involve a CA even for a relatively small repatriation? For straightforward, smaller transactions, the process may be simpler, but involving a CA — even briefly — helps confirm you’re using the correct forms and haven’t missed a DTAA opportunity that could reduce your tax outflow.
If you’re an NRI trying to plan a repatriation, or want to understand the tax implications before you sell an investment in India, our team at Pitanga Wealth can help you think through the process and connect you with the right documentation steps.
This article is for general educational purposes only and does not constitute tax, legal, or investment advice. FEMA regulations, RBI repatriation limits, TDS rates, and DTAA provisions are subject to change and depend on individual circumstances and country of residence; please consult a qualified chartered accountant or tax advisor before undertaking a repatriation or relying on any tax treatment described here. Pitanga Wealth is an AMFI-Registered Mutual Fund Distributor (ARN-134606); mutual fund investments are subject to market risks.
Written by the Pitanga Wealth team.
Enjoyed this breakdown? We post explainers like this regularly on Instagram — follow @pitangawealth to catch them as they drop.
This article is for educational and informational purposes only. It is not investment, tax, legal or insurance advice. Consider your circumstances and relevant documents before making a financial decision.