

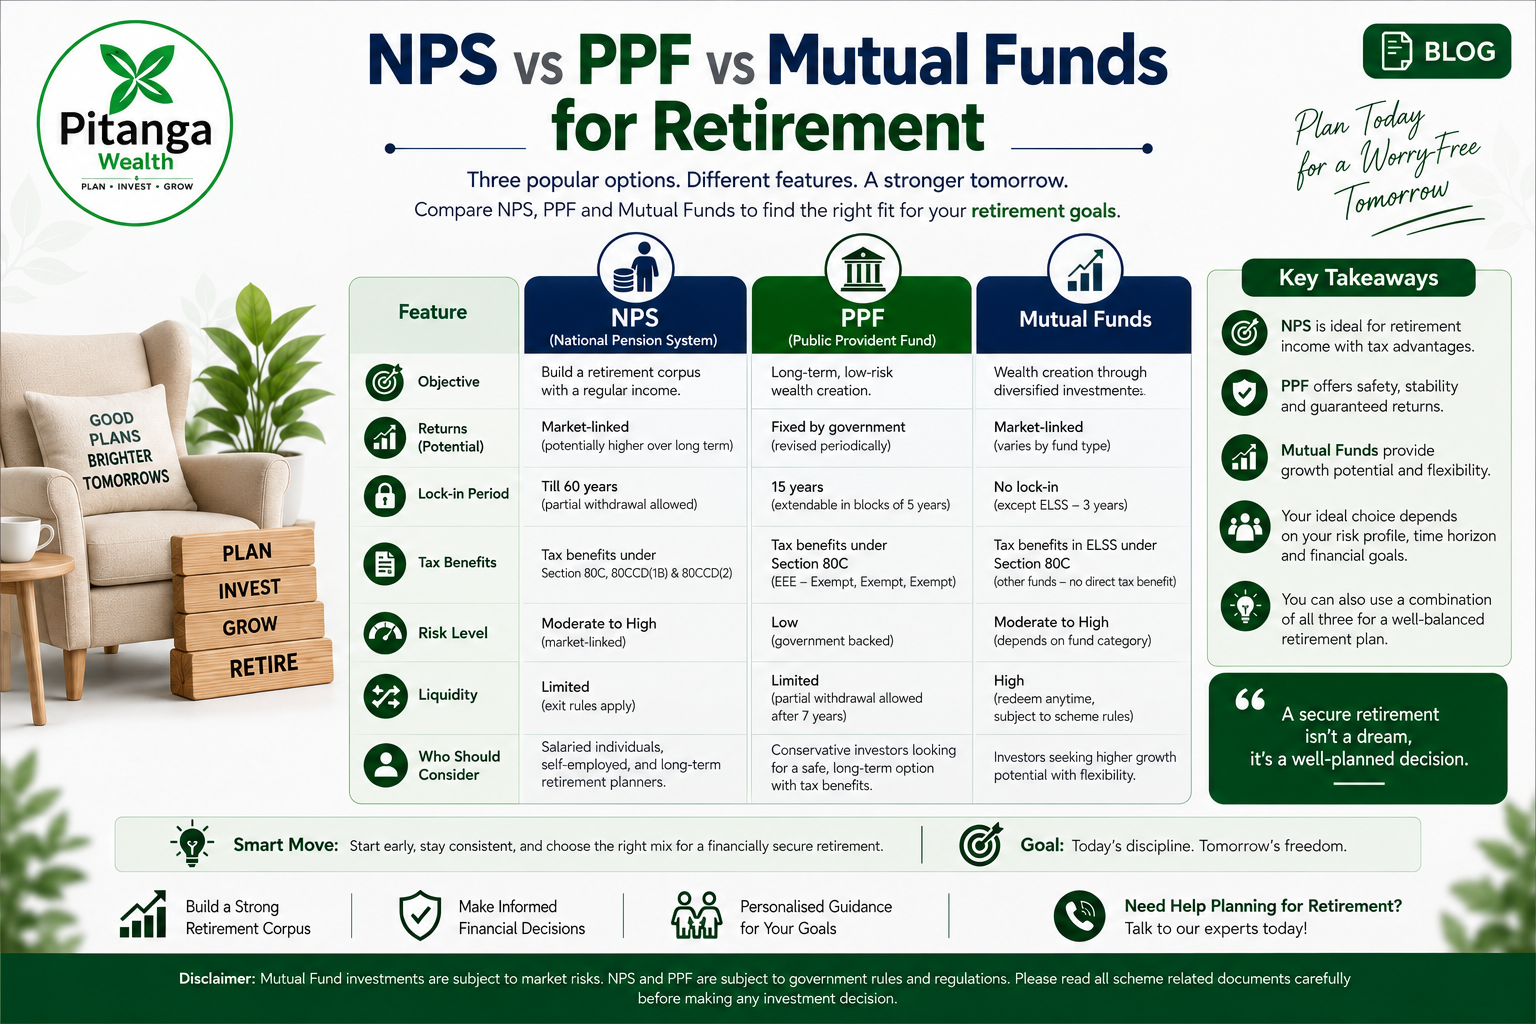
A relative of mine started asking around about retirement planning a few years back, and got three completely different answers within the same week. His bank relationship manager pushed NPS for the extra tax benefit. His father insisted PPF was the only “safe” option worth considering. A colleague swore by mutual funds for the long-term growth. He came away more confused than when he started, mostly because each person was describing one option’s strengths without explaining how it actually compared to the others.
NPS vs PPF vs mutual funds isn’t really a competition with one winner — each is built differently, serves a different purpose, and most serious retirement plans in India end up using more than one. Here’s how they actually differ, so the choice makes sense rather than depending on whoever you spoke to most recently.
What Is NPS?
The National Pension System (NPS) is a government-regulated retirement scheme overseen by the Pension Fund Regulatory and Development Authority (PFRDA). You contribute regularly, and your money is invested across a mix of equity, corporate debt, and government securities, based on an allocation you can typically choose within regulatory limits.
A few things that define NPS specifically:
- It offers an additional tax deduction beyond the standard 80C limit — up to ₹50,000 under Section 80CCD(1B), on top of the ₹1,50,000 combined 80C limit, as per current tax provisions.
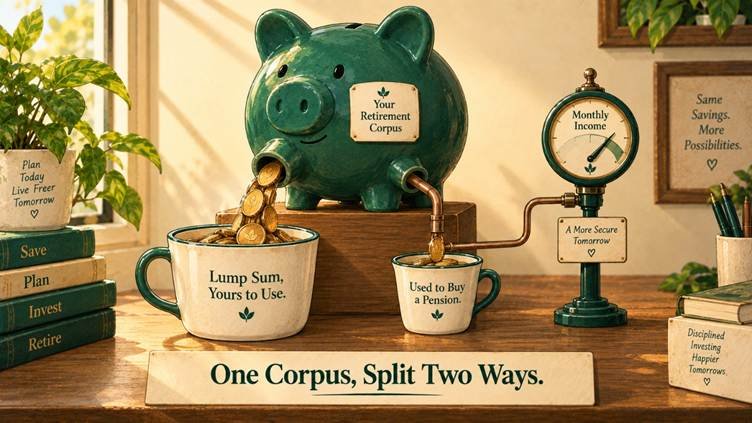
- It has a unique withdrawal structure. At retirement, a portion of your NPS corpus (currently a minimum of 40%, as per prevailing PFRDA rules) must be used to purchase an annuity, which then pays you a regular pension. The remaining portion can typically be withdrawn as a lump sum.
- Returns are market-linked, since a meaningful portion of the corpus is invested in equity and debt markets, so the eventual corpus isn’t fixed or guaranteed the way a PPF balance effectively is.
What Is PPF?
Public Provident Fund (PPF) is a government-backed, fixed-return savings scheme, and one of the most familiar 80C tax-saving instruments in Indian households.
The core structure:
- The interest rate is declared by the government and reviewed quarterly — it isn’t market-linked, so it doesn’t fluctuate with equity or debt markets the way NPS partially does.
- The lock-in is 15 years, with partial withdrawal permitted from year 7 and the option to extend in blocks of 5 years after maturity.
- It follows an EEE (Exempt-Exempt-Exempt) tax structure under current rules: contributions are deductible, interest is tax-free, and maturity proceeds are tax-free too.
What About Mutual Funds for Retirement?
Unlike NPS and PPF, there’s no single “retirement mutual fund” category with special rules — retirement planning through mutual funds generally means using equity, hybrid, or dedicated retirement-oriented fund schemes as part of a long-term investment plan aimed at that goal.
What makes this route different:
- There’s no mandatory lock-in tied to your retirement age for most mutual fund categories (retirement-specific schemes may carry their own lock-in or exit load structure, which varies by scheme).
- You retain full flexibility over withdrawals, unlike NPS’s mandatory annuitization — you decide when and how much to redeem, subject to the specific scheme’s terms.
- Returns are entirely market-linked and not guaranteed, the same as any other mutual fund investment, and the value can go up or down based on market conditions.
NPS vs PPF vs Mutual Funds: The Core Comparison
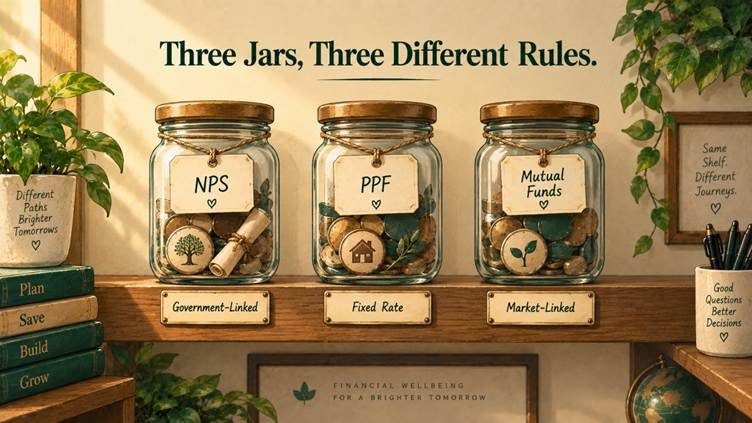
Laid out side by side, the structural differences between NPS, PPF, and mutual funds become much easier to compare directly:
| NPS | PPF | Mutual Funds | |
| Regulator | PFRDA | Government of India | SEBI |
| Return nature | Market-linked (equity + debt mix) | Fixed, government-declared | Market-linked, not guaranteed |
| Lock-in | Until retirement age, with specific exit rules | 15 years (partial withdrawal from year 7) | Varies by scheme; no mandatory retirement lock-in for most |
| Tax benefit | 80C plus additional 80CCD(1B) | 80C (EEE structure) | ELSS qualifies for 80C; other categories don’t |
| Withdrawal at maturity | Minimum portion mandatorily annuitized | Fully accessible, tax-free | Fully flexible, subject to applicable capital gains tax |
| Liquidity before retirement | Limited, specific partial withdrawal conditions | Limited, partial withdrawal from year 7 | Generally more flexible, scheme-dependent |
The Detail Most People Miss: NPS’s Mandatory Annuitization
This is worth pulling out separately because it genuinely surprises people who haven’t looked closely at NPS before committing to it. Unlike PPF or mutual funds, where the entire maturity value is yours to use however you choose, NPS requires a portion of your corpus — currently a minimum of 40%, under prevailing rules — to be used to buy an annuity. That annuity then pays you a regular pension, but the underlying amount used to buy it typically isn’t available to you as a lump sum, and annuity income is taxable as per current provisions.
This isn’t a flaw in NPS — it’s actually the mechanism that gives you an income stream in retirement, which the other two options don’t provide by design. But it does mean NPS is structurally different from PPF or mutual funds in a way that matters when deciding how much to allocate to it versus the other two.
Comparing the Tax Benefits Specifically
Since tax efficiency is often a major reason people pick one option over another, it’s worth being precise about how it currently works, since NPS vs PPF vs mutual funds differ meaningfully here:
- PPF offers full EEE treatment within the ₹1,50,000 combined 80C limit.
- NPS offers 80C benefit plus the additional ₹50,000 deduction under 80CCD(1B), making it the only one of the three with an exclusive extra deduction beyond the standard 80C ceiling — though withdrawal and annuity taxation have their own specific rules.
- Mutual funds only get 80C treatment through the ELSS category specifically; other mutual fund categories used for retirement don’t carry a Section 80C benefit, and gains are taxed under capital gains rules based on the fund type and holding period.
Tax rules across all three are subject to change, and the old-versus-new tax regime choice affects whether these deductions apply to you at all — worth confirming your specific situation with a tax advisor.
Which Might Actually Suit Your Retirement Plan
There’s no single right answer, but here’s how the trade-offs generally play out:
NPS tends to appeal to those who:
- Want the additional tax deduction beyond the standard 80C limit
- Are comfortable with a market-linked corpus and the mandatory annuitization structure
- Want a built-in mechanism for regular pension income after retirement
PPF tends to appeal to those who:
- Want capital protection and predictable, government-backed growth as part of their retirement mix
- Are comfortable with a long lock-in in exchange for safety and tax-free returns
Mutual funds tend to appeal to those who:
- Want maximum flexibility in when and how they access their retirement corpus
- Are comfortable with market-linked risk in exchange for growth potential over a long horizon
- Already have a broader financial plan and want retirement savings integrated with (not separate from) their other investments
Do You Have to Choose Just One?
For most people, no — a combination often makes more sense than picking a single winner among NPS, PPF, and mutual funds. Using NPS for the extra tax benefit and forced retirement discipline, PPF as a stable, low-risk anchor, and mutual funds for flexibility and growth potential is a common approach, with the specific split depending on your risk comfort, tax situation, and how many years remain until retirement.
A Common Mistake Worth Avoiding
Committing heavily to NPS without understanding the annuitization requirement until retirement actually arrives is one of the more avoidable planning mistakes. Similarly, relying entirely on PPF for retirement can mean growth that doesn’t keep pace with rising costs over a multi-decade horizon, while relying entirely on market-linked mutual funds without any stable component can leave a retirement plan more exposed to market timing than most people are comfortable with close to retirement. Understanding each option’s structure before committing significant amounts is worth the time it takes.
At the end of the day, NPS vs PPF vs mutual funds isn’t a question with one correct answer — it’s a question of which trade-offs you’re comfortable with, and most retirement plans end up drawing on more than one.
Frequently Asked Questions
Can I invest in NPS, PPF, and mutual funds all at the same time? Yes, and many people do exactly this as part of a diversified retirement plan, subject to each instrument’s own contribution limits and rules.
Is NPS better than PPF for retirement? Neither is universally better — NPS offers an extra tax deduction and market-linked growth potential but comes with mandatory annuitization; PPF offers predictable, government-backed returns with more withdrawal flexibility at maturity. The better fit depends on your comfort with market risk and how you value the additional tax benefit.
What happens to my NPS corpus if I switch jobs? NPS is portable across employers and even between employment types (salaried, self-employed), since the account belongs to you as an individual, not tied to a specific employer.
Can I withdraw my full PPF balance before 15 years in an emergency? Partial withdrawal is permitted from year 7 onward under specific conditions, but full premature withdrawal is generally not permitted except in specific circumstances like serious illness, as per current rules — it’s worth checking the latest provisions before assuming full access.
Do mutual funds used for retirement need to be equity funds specifically? Not necessarily — many retirement plans use a mix of equity and debt mutual funds, often shifting toward more debt as retirement approaches, similar to the glide-path approach used for other long-term goals.
Is the NPS annuity income guaranteed for life? The annuity itself typically provides regular payouts for life once purchased, based on the specific annuity plan chosen at retirement, but the exact terms, payout structure, and taxation depend on the annuity provider and plan selected — this is worth understanding in detail closer to your retirement date.
If you’re trying to figure out how NPS, PPF, and mutual funds should fit together in your own retirement plan, our team at Pitanga Wealth can help you think through the right mix for your goals and timeline.
Mutual Fund investments are subject to market risks. Read all scheme-related documents carefully before investing. NPS is regulated by PFRDA and subject to its own scheme rules; tax benefits under Section 80C and 80CCD(1B) are subject to prevailing tax laws and the tax regime you have opted for. This article is for educational purposes only and does not constitute investment, tax, or financial advice. Pitanga Wealth is an AMFI-Registered Mutual Fund Distributor (ARN-134606).
Written by the Pitanga Wealth team.
Enjoyed this breakdown? We post explainers like this regularly on Instagram — follow @pitangawealth to catch them as they drop
This article is for educational and informational purposes only. It is not investment, tax, legal or insurance advice. Consider your circumstances and relevant documents before making a financial decision.