

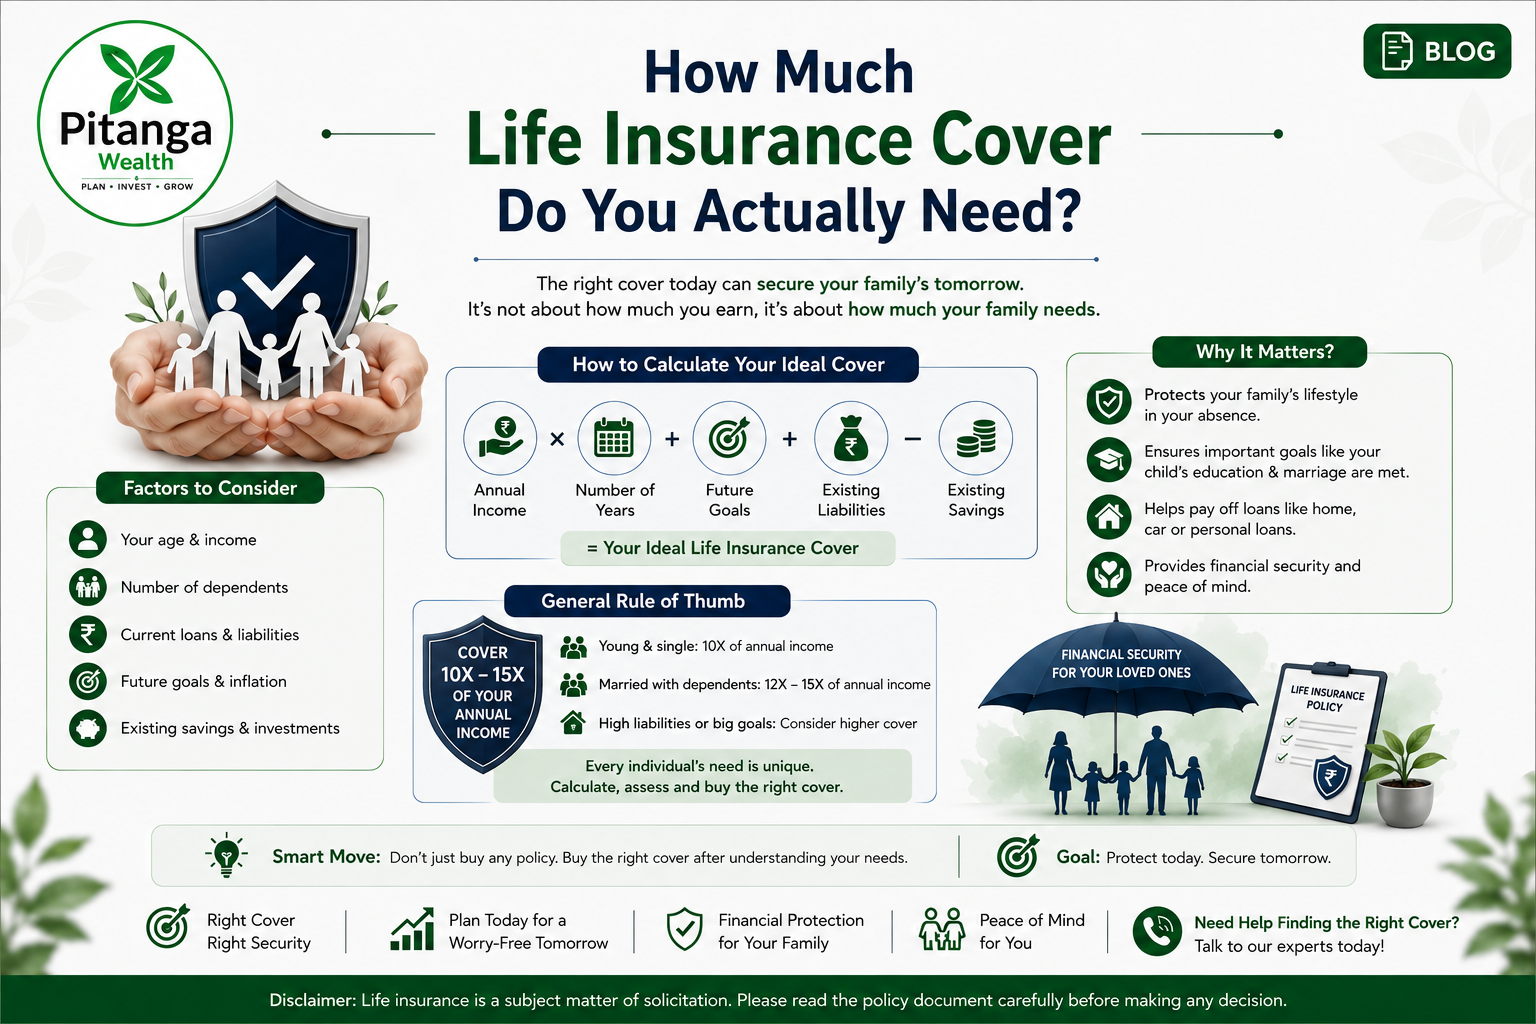
A friend once told me he’d bought a term insurance policy for ₹50,00,000 right after his first job, felt good about it, and never thought about it again — through his marriage, two kids, and a home loan taken eight years later. When he finally sat down and did the math, he realised that ₹50,00,000 wouldn’t come close to covering his family’s actual needs anymore. He wasn’t underinsured because he’d been careless. He was underinsured because “how much life insurance cover do you need” isn’t a question with a single answer that stays right forever — it changes as your life does, and most people only revisit it when something prompts them to.
This is one of the most common gaps in Indian households’ financial planning: not the absence of insurance, but cover that was right for a version of life that no longer exists. So let’s actually work through how to think about the number, rather than picking one that sounds reassuring.
Why “I Have Some Cover” Isn’t the Same as “I Have Enough”
Term insurance exists to replace your income for the people who depend on it, if you’re no longer there to earn it. That means the right amount of cover isn’t a round number that feels sufficiently large — it’s a number tied specifically to what your dependents would actually need: years of expenses, outstanding debts, and future goals like children’s education, minus whatever savings and other assets they could already fall back on.
Buying a policy for whatever amount felt affordable at the time, or matching a number a colleague mentioned, is how a lot of people end up with cover that looks fine on paper but wouldn’t actually carry their family through if it were ever needed.
Method 1: The Income Replacement Approach
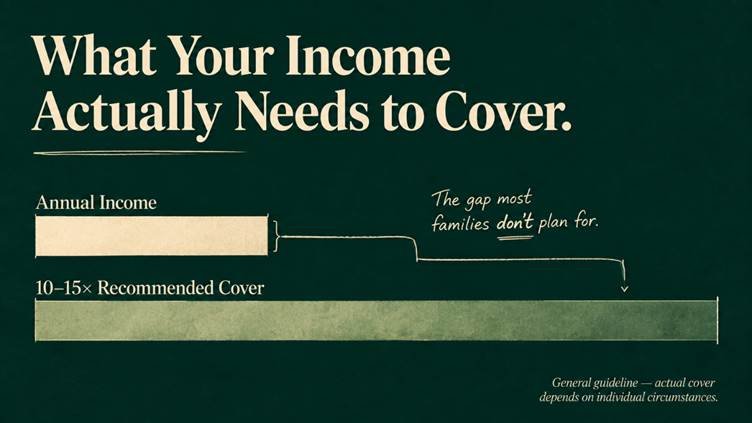
This is the most commonly used starting point, and it’s fairly intuitive: your life cover should be able to replace your income for the years your family would need it.
A frequently used rule of thumb is 10 to 15 times your annual income. So someone earning ₹15,00,000 a year might look at a cover of roughly ₹1.5 crore to ₹2.25 crore as a starting range — not a fixed prescription, but a reasonable place to begin the conversation.
This method is simple, but it has a real limitation: it doesn’t account for your specific debts, your family’s specific future expenses, or what assets you already have. Two people earning the same income can have very different actual needs — one might have a paid-off home and no dependents beyond a spouse, the other might have a 15-year home loan and two young children.
Method 2: The Expense and Liability-Based Approach
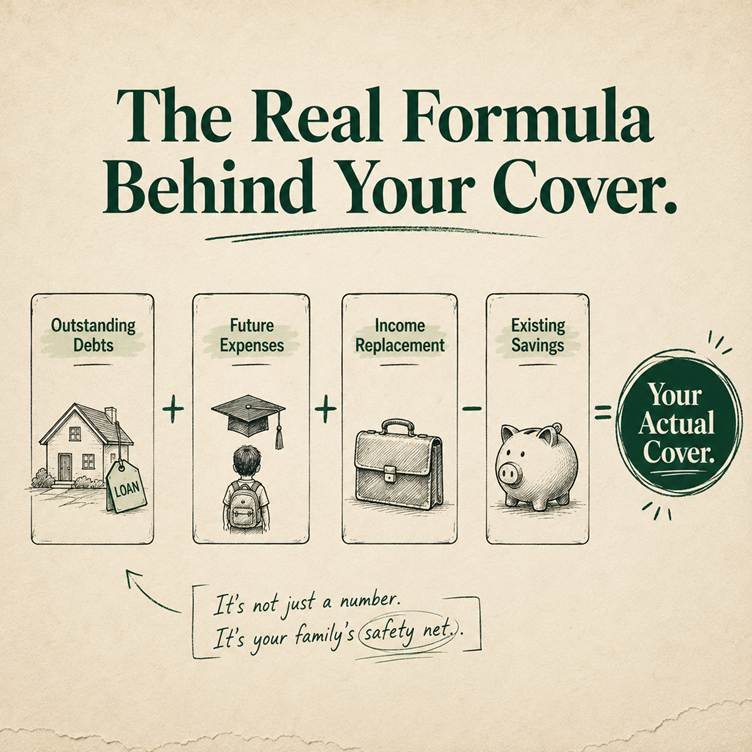
This method builds the number from the ground up, based on what your family would actually need to cover, rather than a multiple of income:
- Outstanding debts — home loan, car loan, personal loans, or any liability your family shouldn’t have to repay alone
- Ongoing living expenses — a rough estimate of your family’s annual expenses, multiplied by the number of years they’d need support (until children become financially independent, for instance, or until a spouse’s own income becomes sufficient)
- Future big-ticket goals — children’s education and marriage costs are the most common ones factored in here
- Minus existing assets and savings — investments, other insurance, provident fund balances, and any other resources your family could draw on, which reduce how much additional cover is needed
Adding up the debts and future needs, then subtracting what’s already available, tends to give a more precise picture than a flat income multiple — though it requires more effort to calculate honestly.
Method 3: The Human Life Value (HLV) Method
This is a more formal actuarial approach, sometimes used by insurance advisors, that estimates the present value of your future earnings over your remaining working years, adjusted for expenses you’d have spent on yourself anyway (since that portion wouldn’t need replacing) and discounted to today’s value.
In practice, most individuals don’t need to run this calculation with full actuarial precision — the income-replacement and expense-based methods above usually get you close enough for a real decision. But it’s useful to know the concept exists, particularly if an advisor references it, so you understand what it’s actually estimating.
What Actually Changes the Number for You
There’s no single universal formula, because the honest answer to how much life insurance cover you need depends on factors specific to your household:
- Number and age of dependents — young children generally mean a longer support period than dependents close to financial independence
- Existing debts, especially long-tenure ones like a home loan
- Whether your spouse also earns, and how much of the household’s needs their income alone could cover
- Your existing savings and other insurance, which reduce the gap that new cover needs to fill
- Your city and lifestyle, which affects what “adequate” ongoing expenses actually look like
This is exactly why a colleague’s number, or a rule of thumb taken at face value without adjustment, often doesn’t translate directly to your own situation.
Don’t Forget Inflation in the Calculation
One factor that’s easy to overlook when working out how much life insurance cover you need: the number you calculate today needs to account for rising costs over the years your family would actually depend on it, not just today’s expense levels. A cover amount that comfortably supports your family’s current lifestyle can fall short a decade in, purely because everyday costs — school fees, household expenses, medical costs — tend to rise over time.
This doesn’t mean you need to build a precise inflation model yourself. It does mean that if you’re using the expense-based method above, it’s worth erring toward the higher end of your estimate rather than calculating tightly to today’s numbers, and revisiting the figure periodically rather than assuming it stays adequate indefinitely.
Why This Number Needs Revisiting, Not Just Setting Once
The friend I mentioned at the start is a common pattern, not an exception. Life insurance cover tends to go stale at predictable moments:
- Marriage — your cover decision now affects a second person’s financial security
- A child’s birth — a new, long-horizon dependent enters the picture
- Taking a home loan — a large liability now exists that your family shouldn’t inherit
- A significant income increase — your family’s lifestyle and future goals typically scale with it, even if your existing cover doesn’t
- Nearing retirement — as debts get paid off and children become independent, the required cover can often reduce, not just grow
Treating your life insurance cover as a one-time decision made in your twenties, rather than something to revisit at these milestones, is probably the single most common reason people end up underinsured relative to their actual needs later.
A Word on India’s Broader Underinsurance Pattern
India has historically had one of the wider protection gaps globally — the difference between the life cover people actually need and what they hold — which isn’t a comment on any one person’s planning, but a reflection of how life insurance is often bought early, cheaply, and never revisited. Recognising that this is a common pattern, rather than an individual failing, is often the first step to actually doing something about it.
There’s no shortcut to how much life insurance cover you need beyond actually sitting down with your numbers — but doing that once, properly, tends to be far more useful than years of vaguely feeling “probably covered.”
Frequently Asked Questions
Is 10 times my annual income always enough life insurance cover? Not necessarily — it’s a commonly used starting point, but it doesn’t account for your specific debts, number of dependents, or existing savings. Someone with significant liabilities or several young dependents may need meaningfully more than a flat 10x multiple suggests.
Should I count my employer’s group life insurance when calculating how much cover I need? You can factor it in as an existing resource, but it’s worth remembering that group cover typically ends when you leave the job, so it shouldn’t be treated as a permanent substitute for your own independent policy.
Does the amount of cover I need decrease as I get older? Often, yes — as debts get paid down and children become financially independent, the amount your family would need to be protected against typically reduces. This is different from the premium, which usually increases with age at the time of buying a new policy.
Can I have multiple term insurance policies instead of one large one? Yes, many people do this deliberately — for example, one policy to cover a home loan tenure specifically, and a separate one for broader income replacement over a longer term. This isn’t unusual and can offer flexibility as needs change over time.
How often should I reassess how much life insurance cover I need? A reasonable practice is to reassess at major life events (marriage, a child’s birth, a new loan, a significant income change) rather than on a fixed calendar, since these events — not the passage of time on its own — are what typically change your actual requirement.
Is it possible to have too much life insurance cover? It’s less common a problem than being underinsured, but cover disproportionate to your actual needs mainly means paying for protection you don’t require. Right-sizing the cover to your real situation, using one of the methods above, tends to be a more useful exercise than simply maximising the number.
If you’re trying to work out how much life insurance cover you actually need — factoring in your income, debts, dependents, and existing savings — our team at Pitanga Wealth can help you think through the right number for your specific situation.
Insurance is the subject matter of solicitation. Please read the policy wordings, exclusions, and terms carefully before concluding a purchase. This article is for general educational purposes only and does not constitute insurance or financial advice; the amount of cover appropriate for you depends on your individual circumstances. Pitanga Wealth is an AMFI-Registered Mutual Fund Distributor (ARN-134606); mutual fund investments are subject to market risks.
Written by the Pitanga Wealth team.
Enjoyed this breakdown? We post explainers like this regularly on Instagram — follow @pitangawealth to catch them as they drop
This article is for educational and informational purposes only. It is not investment, tax, legal or insurance advice. Consider your circumstances and relevant documents before making a financial decision.